Choosing Buyer’s Agents By Commission Rebate: Penny Wise, Pound Foolish

I got this email the other day, responding to one of my <a href=”http://www.danmelson.com/properties_worth_checking_out/”target=”_blank”>Hot Bargain Properties posts on my other site:

I am currently working with a coworker with no agreement. However, she has offered to rebate 50% of her commission. Are you negotiable with your commission?

I am very ready to buy a place at a bargain or discounted price. I have been pre approved by DELETED for $550 but I do not want to spend more than $525, preferably around the $450 range.

I have sufficient liquid funds for 10% down and have an excellent credit score…score 3 months ago was 752.

Let me know.

Now, I do have lower cost and commission rebate packages for when buyers bring me transactions that have the property at least settled upon. The reason is that not only is there much less work to be done done, but I’m providing a lot less value in those circumstances. I’m not going out and going over dozens of properties, eliminating eighty percent of them before taking them around to see the good stuff. I’m not doing background checks on all those properties, looking for issues. At the point that the property is settled on, at least half of the value a good buyer’s agent brings in is already moot. We’ve already dealt with the issue of which property (or properties) are worthy of making an offer on. Now we’re down to negotiations, where I still provide a lot of value, facilitation of the transaction, which any real estate agent worthy of their license can do, and looking out for problems, which starts earlier when I’m locating the property, but when you have title companies and building inspectors and appraisers getting into the act and getting paid, it becomes easy. It’s no longer a matter of spotting the issue before an offer is made, it’s a matter of dealing with the issue if and when it pops up. Much easier, much less time consuming, and much less liability on my part. When you’ve decided to make an offer before I even come into the picture, there is no issue with did my representations cause you to make an offer on the property when you would not otherwise have done so. I haven’t been sued yet, but that’s the number one cause of real estate lawsuits. Sometimes it’s an unscrupulous agent telling the folks that the airport is going to close, but sometimes it’s also people who think the agent said something they did not in fact say, and sometimes it’s people who make something up stuff due to buyer’s remorse. If you’ve already decided to make an offer, that whole issue is gone. Liability? Much less. Amount of work done and time invested? Way less. Amount of value provided to buyers? Also much lower. So yes, I’ll work for less in those situations.

When I find the property, I retain the entire commission.

Yes, getting half the buyer’s agent commission seems like a good idea on the face of it. One to 1.5 percent of a purchase price in the hundreds of thousands of dollars. But how much value do those agents really provide? Consider: Did that agent find you something as interesting as the property they emailed me on? If the agent they were working with was finding them properties like that, there would be no need and no interest in working with me. If she spent enough time shopping the market that she even knows what is and is not a bargain, this person would never have contacted me. Does she look for problems and issues or does she just say “Here is the living room,” and try to talk you into making an offer on every property? What value is that other agent providing you? If the answer is, “not much,” then no wonder she’s willing to rebate half the commission! As far as she’s concerned, the half she does keep is free money for going around and looking with you. My goal is that my clients end up with at least 10% they would not have had without me – either a better property for the same money, or the same value property for a lower price, or some combination of the two. Now, if getting half of a two point five percent commission via rebate sounds better than saving 10% of the value of the property, or getting a property 10% more valuable for the same price, by all means keep shopping agents who rebate commission. If getting a property that is worth more, or paying less for the same property, is what you are after, you need someone who is likely to deliver that, and those discounters business model does not allow them to invest the time and energy to do so. Quite frankly, if they don’t make a habit of it, they aren’t likely to have the necessary expertise, even if they wanted to.

You may ask about how this squares with my attitude about loans. Yes, I’m one of the deepest loan discounters there is. That’s because a loan is a loan is a loan, as long as it’s on the same terms, and most folks qualify for better loans than they get. A thirty year fixed from National Megabank is the same loan as a thirty year fixed from the Bank of Nowhere in Particular, provided the rate, costs, and terms are the same. Only difference is who you make the check out to.


No two properties are alike. Especially in the current market, the difference between shopping smart and not doing so is multiple tens of thousands of dollars, far more than a commission rebate. I don’t rebate buyer’s commissions because I provide more than that in value. In my estimation, and that of the people who are working with me, it’s money well spent. You get what you pay for.

Good buyers agents make a habit of looking for real bargains, whether or not they have a client it’s appropriate for. It’s called market knowledge. With market knowledge, a good agent can not only identify the ones that are bargains, you are able to negotiate better terms on those bargains. Good buyer’s agents usually have bargains they know about that they just haven’t found the appropriate client for yet. If you’d like to work with them and get shown these bargains, or have them go looking for bargains specifically for you, there is a price to be paid, and that price is that they make a little more money than the do-nothing discounter. You don’t pay it, at least not directly, the listing agent does, and through them, the seller. If you believe that the final price might be somewhat higher to reflect that, you would have some justice on your side, provided you don’t consider the value in locating the bargain property, the value in negotiating for a better price, and the value in avoiding problems before they happen, or dealing with them in initial negotiations rather than at the end of escrow. If you don’t see the value, then not only are you saying that you don’t see the solution, but that you don’t understand that there is an issue. This indicates someone on the first level of competence: The unconscious incompetent. Not only do you not know how to do it, you don’t realize that there is acquired knowledge and acquired skill involved.

Now a good agent who knows they provide value should have no difficulties asking only for a non-exclusive buyer’s agent contract. if you don’t like what that agent does, if you do not agree that there is value in that agent’s approach, this leaves you free to stop working with them at any time and go work with someone else. If the agent doesn’t perform, as in find and deliver a property that you agree is more “bang for the buck” than you would otherwise have gotten, by all means go work with the bump on a log who splits the buyer’s commission with you.

If you want a Yugo agent that breaks down in the middle of the transaction and leaves you stranded, that’s no skin off my nose, but you are not the client I’m looking for and the bargains I find are for my clients. I am neither obligated nor inclined to share them with people who want to use some other agent. Go find them yourself if you don’t think I’m providing value. Just the knowledge that something like that is available should be a large amount of help. But if you can’t, perhaps you might consider that perhaps I might be providing a certain amount of real value for my pay?

Very few people reading this are likely to be receiving minimum wage for their employment. If you are not prepared to concede that it is possible for more skilled, more knowledgeable people to deliver a more valuable product, whether that product is service or commodity, what possible justification do you have in making more than minimum wage? For that matter, unless you are one of those people whose work has to be done on site, why isn’t your job being done by some subsistence level worker in a Fifth World hellhole? Even if we limit ourselves in the application of this principle to qualified and licensed people here in the United States, my guess is that your boss could probably hire other people to do your job more cheaply, but his additional investment in you probably makes him more money than that cheap replacement worker would save, and that’s the reason you are worthy of your pay. This very same reason is why I am also worthy of my pay.

By the characteristics they are claiming, the person with the email at the top of the article is a very qualified buyer. Don’t you think that should be working with someone who knows how to use that as leverage to get them a better bargain? Suppose they weren’t. Don’t you think it might be in their best interest to have an agent who knows how to structure a transaction so that it can work, and can help avoid wasting time and money on properties and transactions where it can’t and sellers who do not have the option of working with them in the requisite way?

Or you can pay full price for a mediocre property, and console yourself with a much smaller amount of cash, that when you consider the entire situation, is a fraction of the money that came out of your pocket but didn’t have to. Pay too much, and get a check back for maybe a fifth of it in cash. Sound like a good deal to you? Maybe you didn’t pay cash for the property, but then you’ve got a loan, and you paid additional fees based upon the size of that loan, and interest because you borrowed that money, and more in property taxes because you paid more than you should have. All of this eats away at money you would otherwise have in your pocket and equity that you would otherwise have in the property. Just because there’s no explicit dollar figure on it doesn’t make it any less real. How would you feel about writing a check drawn directly on your net worth for some unknown amount? Not so hot? That’s what you are doing by using some bump on a log discounter who basically allows you to keep a percentage of what they provided no real value to earn. This is one of the largest transactions of your life. Scrimping on the compensation of the person who has the knowledge and skills to save you many times what they cost is almost as intelligent as OJ Simpson hiring a cheap lawyer. Even though I hope that you haven’t been accused of murder, using a less skillful agent means you wasted money. Even though that’s not a crime and you did it to yourself, it’s still nothing beneficial to your overall financial picture.

Caveat Emptor
Can I Afford This Property?

Cold Hard Fact for today: The average Real Estate Agent or Loan Officer is not motivated to tell you that you can’t afford your property.

For the agent you are trying to talk people out of a property after they have already fallen in love with it. Let’s face it, if it’s higher in price, it should have features that lower priced properties do not, and it should have fewer things that consumers do not want. Indeed, one of the easiest and most common ways unethical real estate agents sell properties is by showing you several lower priced properties, fixers which lack those attractive extras, then show you the blinged out immaculate property while whispering sweet nothings like, “I can show you how you can afford the payments!” (which is not the same as being able to afford the property!)

All agents learn that by telling the client “no,” or anything that sounds like “no,” they are likely to lose that business. Good ones know that putting a client into something beyond their budget is a good way to have the transaction come back to haunt them. But for most, the temptation of the easy sale that made itself if too strong. They want that commission check. Nothing wrong with commission checks. If they provide real value to the client, they are a way of showing the world that you have done something valuable, same as a doctor, carpenter, or computer programmer. It’s when you use your position of trust to sabotage them that problems start – and you should experience problems. Many agents have not been around long enough to understand flat or declining markets. In truth, I wasn’t in the business the last time we had one, either. But I am old enough to remember, and careful enough by nature that I refuse to assume that a rapidly rising market will save my bacon, as many agents have become used to.And for the foreseeable future, rapidly rising markets are unlikely to save anybody’s bacon, because the market isn’t going to be rising rapidly. Inventory is high, long term rates are set to rise, and we’re just seeing the leading edge of a wave of problems caused by over-the-top practices of the last few years. I think we’re past most of the price decline locally, but conditions aren’t there for a return to the market we had most of the last decade.

Lest you be wondering, the loan officer is even more unlikely to counsel you on whether you can really afford the property. Between Stated Income, Negative Amortization Loans, and loans that are both of these, you can get anybody with an income and a not too putrid credit score into the property. In fact, I heard some real howls of outrage from certain brokers when lenders tightened their recourse on brokers this last year. Even so, the paycheck is now and certain, the risk of default vague and indefinite, and for most loan officers, there’s another concern as well.

You see, most loan officers cultivate some friends who are real estate agents, and that’s how they get their business. That agent brings them business because they have a history of getting the loan through, so that agent gets paid. Sometimes they may have their hand out for a referral fee as well, but the important thing for you to know as a consumer is that referral you get from an agent to a loan officer has nothing to do with how great their rates are, and everything to do with how creative they are in getting some sort of loan approved so that agent gets paid for the house they sold. Tell just one prospect who has made an offer on their dream house that there is an issue with being able to really afford that loan, and the word will get around the real estate community in no time. Result: For causing one agent to not get paid, Joe Loan Officer not only will not get any referrals from them in the future, if the client does find Joe Loan Officer on their own, the agents are going to do their best to talk them away from Joe, who, from their point of view, “stole their paycheck” by telling the client that they really could not afford the loan that was necessary to make the transaction work! Even if they took that transaction to some other loan officer who got it closed, Jane Realtor doesn’t want her clients to have anything to do with Joe, lest she lose another potential commission check!

So what can you, the consumer, do about this? Well, I can’t tell you all about the special cases, and I lack the programming capability to embed a spreadsheet and loan calculator. But I can give you some good general rules of comparison, and guidelines laid down by lenders as to whether or not you can actually afford that loan.

Start with your total monthly gross income. Assuming you printed this out, write that number here:

Loan Type
A Paper ARM
A Paper fixed
sub-prime general
sub-prime severe
sub-prime extreme

Multiply Income by (DTI*)
0.38
0.45
0.50
0.55
0.60
Result
_______
_______
_______
_______
_______

Notes
A,B
B


*DTI: Debt to Income Ratio

Notes:
A: use fully indexed rate for qualification purposes. This means the underlying index plus the margin after it adjusts, assuming current values.
B: If interest only, use fully amortized rate for qualification purposes.

Any four function calculator will do this much. Now this is the largest number you will qualify with. As you should be able to see, it’s more difficult to qualify for A paper, even though that is where you want to be. But we’re not done. This is total housing and debt service, the so-called “back end ratio.” So from that number, you need to subtract your monthly debt service: Car payments and other installments, and minimum credit card payments. You pay this much already. You obviously cannot afford to pay it out for housing also!

So add up your credit card, car payment, and other monthly debt obligations. Subtract it from your numbers for back end ratios, computed above. This will give you a set of five numbers that tells what you can afford for housing costs, depending upon how far you want to go. But we’re not done! This is total cost of housing; the so-called “PITI payment.” It includes not only principal and interest on the loan, but also property taxes, homeowner’s insurance, Condominium Association dues, and Mello-Roos assessment districts (or their equivalent outside of California, if applicable). So from this, you need to subtract all of the known stuff or stuff you can make a close approximation on, like Association dues and insurance and taxes, to arrive at how much of a loan you can afford. Please note that for Negative Amortization Loans, loan officers may use the minimum payment for qualification, but you are still being charged the real interest rate! Still, it should become obvious as to why Negative Amortization loans are so popular in high priced areas right now. Not only will the lenders pay between 3.5 to 4 percent commission for them, not only do they allow lower payments to be quoted, but they make it look like you qualify for a bigger loan than you can afford, which means the real estate agent gets a bigger commission from selling you a more expensive property, and the loan officer gets paid more, also, because now you have applied for a larger loan! I have heard every rationalization under the sun from loan officers and real estate agents on this score, but they are still inappropriate for the vast majority of people who have them. I can get a better interest rate on a better loan for less cost, every time, but then I have to tell the client about the full amount they are really being charged every month, and they might have to content themselves with a less expensive property, meaning that real estate agent is going to have to do some real work. Go out onto the web and look for some loan calculators (Auto loans use slightly different assumptions, so don’t use those calculators), or if you have a financial calculator, use it! Use the real interest rates that are available, and if the number you get comes out much higher than your quoted payment, they are trying to snooker you with a negative amortization loan. There is no magic about loans, and a healthy skepticism will help you prevent problems from happening in the first place.

Now add the down payment you intend to make to the loan you can afford, and that tells you whether or not you can afford the property.

Caveat Emptor

Short Sales of Real Estate, aka Short Payoffs

A while ago I wrote an article called, “What Happens When You Can’t Make Your Real Estate Loan Payment.” This is kind of a continuation of that, as I got a search that asked, “What is necessary to persuade a bank to accept a short payoff on a mortgage”

Poverty. In a word, poverty. You have to persuade the bank that this is the best possible deal they are going to get. You can’t make the payments, and if they foreclose they will get less money.

A “short sale” or short payoff is defined as a sale where the proceeds from the sale will not cover the secured obligations of the owner. The cash they will receive from the sale is “short” of the necessary amount. The house is no longer worth what they paid for it.

When I originally wrote this article, I was looking ahead. There were more and more of these happening, but the big wave had yet to hit. That wave has now mostly passed. There are always people that lost their good job and can’t get a replacement nearly as good. But for a while, there were also people that were put into too much house, and approved for too much loan, suddenly discovering their situation was not sustainable because they suddenly couldn’t make the payments. Unscrupulous agents that wanted a bigger commission, loan officers going along, and nobody acting like they were responsible for the consequences to their clients. My concern for lenders who do stated income and negative amortization loans (and a lot of loans that are both!) is kind of minimal. Okay, it’s very minimal. Like nonexistent smallest violin in the world playing “My Heart Cries For Thee” level sympathy. I forecast years ago that many lenders were going to go through bad times, using a forecasting method that’s about as mysterious as rocks that fall when you drop them.

On the other hand, for the people who were led into these transactions by agents with a fiduciary responsibility towards them, I have great heaping loads of sympathy and I’ll do anything I can to help. Yes, they’re theoretically responsible adults, but when the universe and everyone is telling them all the things that buyers were told these last couple of years, it’s understandable. Sure there’s a greed component in many cases but when they’re told by both loan officers and the real estate agents that they “wouldn’t have qualified for the loan if you couldn’t afford it,” they are being betrayed by the same people who are supposed to be professionals looking out for their interests. I really do suggest finding a good lawyer to these folks, as those agents who did this to them (and their brokerages) better have had insurance which said lawyer can sue to recover money they never should have been out.

I’m going to sketch it out in broad terms, but there are a lot of tricks to the trade. Short sales are not something to try “For Sale By Owner,” or even with a discount agent.

First off, you need to draw a coherent picture of the loan payment being unaffordable. If you were on a negative amortization approaching recast, or hybrid ARM (usually interest only for the fixed period) that is now ready to adjust, you’re facing a much higher payments. Even if you were able to afford the minimum payment before, now you can’t and you’ve decided to sell for what you can get before it bankrupts you to no good purpose because you’re going to lose the house anyway. You’re going to have to prove you can’t afford your loan. The bank isn’t just going to accept your word, but several late payments or a rolling sixty day late that looks headed for ninety have been known to be persuasive. If you can afford the payments but have merely convinced yourself you don’t want to, please read Why You Should Not Walk Away From Upside-Down Real Estate. Nonetheless, there are a lot of tacks that you don’t want to take. Remember, lenders want to be repaid and they’ve got a couple of pretty powerful sticks to shake at you. They are not going to agree to sacrifice money merely because to make the payments would be uncomfortable for you. You’re going to have to persuade them it’s impossible.

Second, you’re going to have to persuade the lender that this is the best possible price that you are going to get, and that even if they think they’ll get more by going through foreclosure, it will be more than offset by what they’ll lose through the expenses involved. Not to mention that they might end up owning the property, which they don’t want to do because then they have to spend more money selling it.

Third, you’ve got to be on the ball about the transaction itself. All the ducks have to be in the row from the start, which is when you approach the lender with a provisional transaction. If they’re not, the lender is just not going to go through the process of approving a short sale until they are. Since this takes time, it has the effect of dragging out the transaction. Every missed deadline means the lender will look at the whole thing again, possibly changing their mind about approving the short sale. You need a qualified buyer. Furthermore, most short sale buyers end up bailing out of the transaction at some point, most often because they don’t think it’s going to get approved on terms that are acceptable to them. You need a full service listing agent who knows what they’re doing to prevent this from happening.

Fourth, just be prepared for the fact that the lender is not only not going to approve the transaction if you get any money, but that they’re also going to send you a form 1099 after it is all done. This form 1099 will report income for you from forgiveness of debt. This is taxable income! Many agents eager to make a sale will not tell the sellers this, and when you get right down to it, there is no legal requirement to do so, but I’ve always thought this was one of the ways to tell a good agent from a not-so-good one. It does seem like something you should be told about before you’ve got the 1099 form in your mailbox, right? At that point, you are stuck with all of the consequences, where if you had known before, you might not have been so complacent. It is to be noted I’ve been made aware of ways to circumvent the “no money to the owner” requirement, but they are FRAUD, as in go to jail for a while and be a convicted felon for the rest of your life FRAUD. It can be tempting, but committing fraud is one of the most effective ways I know to make a bad situation worse.

For the buyer, short sales can seem attractive for any number of reasons. Typically the seller is in a situation where they have to sell, and everyone knows it. The option of waiting for a better offer really isn’t on the table if what you’re offering is anything like reasonable. They can’t bluff you, they should know that bluffing you is a waste of effort, and somebody should have explained to them that they really just want out now (and why this is so) before it gets worse. What’s not to like? The answer is the fact that there’s a third party with veto power over the transaction. The sellers don’t have must motivation to bargain hard because they’re not getting any money anyway, but many lenders are stuck in the land of Denial.

Your competition will also make things difficult. Because people think there’s fast money to be made, these folks are the target of “flippers” everywhere. The large city, highly inflated markets more so than most. A couple weeks before I originally wrote this, we put one on the market and got three ugly low-ball offers within 48 hours, and this is part of why you need an agent to sell one. Remember, the seller isn’t getting any money, but they are going to get a 1099 form that says they have to pay taxes. Don’t you think most folks would rather it was for less money, and therefore, less taxes, instead of more? The more money the lender loses, the higher your liability. Had any one of the three made a better offer in the first place, they would have gotten the property at a price to make a profit, but they had to prove how rapacious they were, or something. As it was, we jawboned the first three vultures and two other, later entries, into a quasi-decent price, with minimal later tax obligation to our seller, and (eventually) got the lender involved to see reason.

In summation, “short sales” are a way to cut your losses for sellers, and a way to maybe get a good price for buyers, but you have to know how to convince the lenders to accept them, and how not to overplay your bargaining position, lest you get left out in the cold.

However, lenders are basically in denial for a variety of reasons, and they do not want to admit that their underwriting was at fault for lending more than the property was likely to be worth, and more than the borrower could really afford. For that reason, short sales are a long hard slog, and many times lenders are rejecting the transaction no matter how much sense it makes. So be advised before you even start that this is an uphill battle, and if the listing agent is not on top of the game, you may be wasting your time making an offer. Quite often, the lender simply says no – that they’re not going to accept this transaction unless someone comes up with more money to make them happy.

Caveat Emptor

Seller Paid Closing Costs (or, When Your Prospective Buyer Has No Money)

In many transactions when I originally wrote this, the buyer has absolutely no money, or an amount that was not sufficient to pay the costs that they would traditionally be expected to pay in order to close the transaction. Today, unless they’re eligible for a VA loan, there is no such thing as a “no down payment” loan, but the trick is to stretch the cash they do have to make the transaction work. In a buyer driven market, often the seller still wants to do business with them.

The usual way it’s handled is in Seller Paid Closing Costs. The Seller gives the buyer an allowance to cover their share of the costs

Lenders have become somewhat tolerant of the practice, at least so long as the appraisal comes in at or above the official sale price. Many of them were starting to revert to the treatment this trick traditionally got, which is to say, if the sale price included a rebate to the buyer, then the sale price as far as the lender was concerned was the official price less the rebate. In other words, seller’s net. Remember, lenders value real estate the same as accountants, on the LCM principal – Lesser of Cost (which is to say purchase price) or market (which is to say the appraised value). If the seller is giving the buyer money back, then the official price listed on the transaction isn’t really the price, is it? Do advertisers tease you with the gross price of stereo or computer gear before the rebate, or the net price after the rebate? Same principle here. The lenders traditionally took this stance, although it has been more relaxed in the highly competitive lender’s market of late, and although they were starting to change back, the dearth of qualified buyers with extra cash has made them reconsider that. The lenders are (typically) not going to lend more money than the lesser of those the two variables, cost and market, and they will base the loan parameters on whichever is less. You can always buy a house for more money than the value, as long as you have the cash to make up the difference.

The Sellers get their house sold. That and the ego thing of the official sale price seem to be the benefits to them. I would certainly rather sell for the seller’s net in the first place, if I’m a seller, without an allowance, because I have to pay commission on that higher amount. A $10,000 allowance (as has become common here) costs the seller $700 to $800 or so in increased costs – agents commissions, title insurance, escrow fees, transfer taxes – even if the sale price is $10,000 higher because of it. This is neglecting the potential effects of taxes due to exceeding the $250,000 (or $500,000) maximum gain exemption from the IRS code Section 121. I recommend against it for sellers unless there is a substantial deposit, as it is often indicative of a not very qualified buyer. Even then, it’s a real good idea to talk to your tax person. Furthermore, with the lenders in full blown panic right now, the only loans being accepted with little or no down are VA and FHA, both of which carry government guarantees. VA can do true 100% financing, but buyers eligible for VA are uncommon. For FHA, the zero down enabling down payment assistance programs are dead, but having 4-6% down for an FHA loan is a lot easier than 10%+ for anything conventional.

The Buyers get a deal, or so it appears at first blush. A piece of property without having to save for closing costs. When I originally wrote this, in many cases they didn’t have to put a penny down, either. Pretty cool, eh? Get a house and actually skip a month of writing a check (due to the allowance covering prepaid interest), so effectively putting cash in your pocket. Keep in mind, however, that a competently advised seller is going to inflate the sales price to match, where (if they were smart) they would rather have accepted the net sales price without rebate. Furthermore, at least here in California, property taxes are based upon official original sales price, so you’ll be paying for it as long as you own the property. Finally, because your purchase price, and therefore your loan, is going to be higher, your payment is going to be higher, you’ll pay higher loan costs every time you refinance, and your eventual net on the property will be lower. If it is the only way to get into the property, and the deal otherwise makes sense, that’s fine – but don’t kid yourself that you got free money. Chances are that you’re going to pay far more than the amount of any allowance because you got it.

If it’s bad for the seller, bad for the buyer, and risky for the lender, why does it keep happening so much?

Well, it’s a sale for sellers. The property has now been disposed of. It’s also an ego defense for sellers. Instead of $470,000, they can tell everyone they got $480,000. So long as they don’t mention the allowance, it sounds like a far better price to their friends, family, and soon to be ex-neighbors. In short, bragging rights. Buyers, it gets them into the property, formerly often without coming up with a penny in cash and still allowing them to save one month’s rent or payment, effectively putting cash in their pocket. Mind you, that unwillingness is going to be costing money for as long as they own the property, but that’s their choice.

Real Estate and Mortgage folks, get bigger commissions. $10,000 in sales price gets translated to $100 per 1 percent of commission. This is anywhere from an extra $100 to an extra $300 or $400 for each of the offices, buyer’s, seller’s, and loan. Furthermore, I know of loan agents who extract larger commissions because “it’s such a hard loan.” It does make the loan harder, but not by another point of origination’s worth. Wouldn’t you like to have extra money for essentially the same work? I assure you that your average real estate agent and loan officer are no different than most folks.

These days, the spoke in the wheel that prevents this from happening is usually the appraisal. With Home Valuation Code of Conduct, most agents in most transactions no longer have the option of steering business to the appraiser who will inflate value as much as possible. I’m not having problems on my purchase money transactions because if appraised value isn’t likely to be there, I advise my clients of that fact. But it’s putting a real crimp on the transaction mills.

There is nothing wrong with the practice of seller paid closing costs, so long as everybody knows what’s going on. But it’s certainly not something you want to do if you have a choice.

Caveat Emptor

Loans On Related Party Transfers of Real Estate – Family, Corporate, or Partners

One of the things that has a lot of issues is any transaction between related people. This is not limited to purely family transactions, but applies also to transfers among partnerships and their partners, corporations and their officers.

The market theory holding that the value of a property is what is agreed to between a willing buyer and a willing seller is subject to the proviso that neither buyer nor seller has a reason to inflate or deflate what the property is worth to them. If the parties are related, there is an obvious reason to think that this may not necessarily be the case. Parents do things for their children all the time, siblings for each other, and as you’re probably aware if you work in corporate America, major stockholders, investors, and executives often manipulate corporate versus personal transactions for less than wholesome reasons. Partnerships do the darnedest things, as well.

The issue, as far as the lender goes, is that they are trying to safeguard their money. Lending is a risk based business, and the lender wants to know that they are not taking more of a risk than they intend to when they take on this loan.

Let’s say Jane Jones is CEO of SuperColossal Corporation. She wants to manipulate her compensation, so she has SuperColossal sell her property for half its real value.

This is actually okay by most lenders, if not securities regulators, IRS agents, et al. The loan is based upon the purchase price, the appraisal comes in double the purchase amount, and the lender assumes less risk than they price the loan for. Remember, the property is valued based upon LCM: Lower of Cost (purchase price) or Market value. When market value comes in high, the lender is covered. What isn’t so cool is if Jane Jones sells SuperColossal the property back at twice its value. If the corporation gets a loan for 75 percent of alleged value, that’s at least a third of the lender’s money they’re not going to get back in case of default, which becomes likely when Jane is fired and the new CEO asks why they are paying the loan when they owe half again what the property is really worth.

Needless to say, the lenders want to guard against that. Many lenders will not do related party transactions, period. For the ones that do, they will want to be very careful on the appraisal, which has now become their only guard against getting into an indefensible position. Many times, lenders may require related party transactions to go through certain appraisers, they may require in house appraisers, they may require multiple appraisals, and they may require that there be no contact between principals and appraisers. Whatever their required precautions, they need to be followed, as failing to do so will cause the loan to be rejected.

I’m going over this to make a point. Many lenders have additional requirements for related party transactions. Some may require full documentation only, others require that the loans have full recourse (they can come after you legally if they lose money). Each and every lender creates their own policy, and if your transaction is between related parties, it is probably more important to inquire about related party transfer policy and requirements than it is to get a good rate at a competitive price. Not much use having a great quote if you can’t meet the lender’s requirements. Even worse if it causes you to waste time with a lender whose requirements you cannot meet, and now your deadline for the transaction is here and you don’t have a loan, and so cannot complete the transaction.

Just to be clear, I’m not talking about legalities of transferring the property. There are comparatively few additional rules about that, most of them coming from securities regulators having to do with corporations engaging in such behavior to the disadvantage of shareholders. This article is talking about the possibility of getting a loan from a regulated lender if you need one to consummate the transaction. Each of them will have rules they institute in order to protect their putative investment from being lost to fraud of one sort or another. The fact that you’re not intending anything fraudulent isn’t important – other people have, and they lose a lot more from one bad loan than they gain from several good ones.

Caveat Emptor

Mortgage Accelerator Programs: A Good Basic Idea, But the Devil Is In the Details

The most recent hot thing in mortgage circles is a mortgage accelerator program. Now I’ve heard other things, most notably biweekly payment programs, called mortgage accelerators in the past, so let me take a moment to define exactly what I’m talking about.

A mortgage accelerator is essentially a combined mortgage and checking account, where every month you deposit your entire pay, and then write checks out of it as the month goes on to pay for your living expenses, and the mortgage interest of course accrues on a daily basis. The good things about it for consumers (and it is a good thing, as far as this goes) is that the entire paycheck is applied against your mortgage balance on day one, when your pay is deposited. This means that instead of just the minimum monthly payment, your entire pay goes towards the mortgage, lessening the amount of interest you pay in any given month. The bank, for its part, gets your entire paycheck and a significantly lower incidence of default.

This isn’t a new concept. Several banks had somewhat different versions back in the late eighties. It went away. Why?

Several reasons, some administrative, some financial. First, the administrative. This bank has basically your entire financial activity. Let’s say someone gives you a better deal. Now you either have to stick with a mortgage accelerator program, or go through the hassle of coming up with enough cash to start a new checking account if you go back to having a standard mortgage. Furthermore, when you do refinance, what happens to outstanding checks? That payoff is as of a specific day at a specific time. Your escrow officer comes in and gets the payoff demand, and then more checks clear and everything has to be re-figured. The alternative to this is freezing the account as is done with Home Equity Lines of Credit. So all of a sudden while you are going through this refinance, you have to come up with the seed cash for a new checking account, get new checks rushed through, and then pay your bills with the new checks. May the Universe Help You if you normally pay by automatic debit or any of the primary variants, because you have to set that up as well.

So what else does the bank get out of it, looking at the above? Increased opportunity costs for refinancing. In short, it makes it more difficult for you to take your business elsewhere. Cha-Ching! as the bank officer’s eyes light up with dollar signs.

Now obviously, this mortgage accelerator saves you money, if you assume it’s just a matter of math, and that math shows how much interest you save as opposed to the same loan at the same interest rate, providing you keep money in your checking account, of course. But how many people do? Not that many, these days.

Furthermore, it assumes you get the same loan at the same interest rate that you normally would. I haven’t comparison shopped many of these yet, but my general impression is that the rates, and costs to get them, are higher than you might otherwise get. The assumption that it is the same rate and the same costs on the same type of loan is just that, an assumption, made for modeling purposes. I have used the metaphor of the matador in the past. The bull (consumer) wears himself out on the obvious large red cape, namely the cool service and the fact that all your pay is applied to your mortgage, and never sees the sword, which is the fact that your interest rate is half a percent higher than you might have gotten, you paid an extra point of origination as well, and you’re being dinged $10 per month administrative tracking charges for this cool new toy you just got, the accelerator mortgage. Let’s say your mortgage is $400,000. Half a percent of $400,000 is $2000 extra interest per year. An extra point of origination is $4000. And $10 per month is about what the average person might save on their mortgage interest if they weren’t paying a higher rate, which they are.

($6000 per month deposited, instead of maybe $2500, leaves $3500. You save an average of one half months interest per month on this difference. $3500 at 6% divided by 24 is $8.75. If they bill you $10 per month for the service, you are out $1.25 per month net, on top of the additional interest charges and the one time fee of several thousand dollars of origination)

So lenders with mortgage accelerators charge you more money, charge you more up front costs, and you pay higher interest charges, as well as making it more difficult for the consumer to refinance into a better deal somewhere else. The banks love this one. Only the fact that your parents figured out what a rotten deal most of these are kept them from becoming a permanent fixture of the mortgage landscape nearly twenty years ago.

Now if you can find a mortgage accelerator at the same interest rate, for the same costs, and without the monthly fees that you don’t have to pay for your other mortgage, then YES it makes a huge amount of sense to have one of these programs. But that’s not what most of the lenders are offering. They are hoping that you are so distracted by the mathematics of how much you will save if you keep your mortgage until it’s paid off, that you will never see how much extra you are really paying. Nor do most people keep any given mortgage longer than a few years. In fact, the median time living in a particular piece of real estate is only nine years – less than one third of the time until payoff. The metaphor of the matador is extremely apt. This is precisely what the matador does with the bull. Distracts them and wears them out with the cape so that they never see the sword. The banks dangle this wonderful mathematical concept of what might happen thirty years down the line for that one tenth of one percent of people who actually keep the loan that long, while hoping you are so fascinated by it that you never notice that they’re charging you more up-front fees and a higher interest rate than you would have gotten with a traditional mortgage, and often, more in monthly maintenance fees that you save by depositing all of your pay. In short, the lender is making more money off of you by pretending to do you a favor.

So shop loans by interest rate and cost, and then if they’ll let you put a mortgage accelerator on it for free, great! If not, they’re just trying to distract you from what is really important by offering you a convenience and a cool-looking trick, while charging you hefty amounts of money and tricking you into thinking you are getting something beneficial.

Caveat Emptor

Loan Rate Sheets: The Games Lenders Play With Rate and Cost Adjustments

This is part and parcel of the system that’s abused. Here are sample rates from one A paper lender, picked at random, that were in effect when I originally wrote this. Rates are lower now, but it’s a good example nonetheless. These were Fannie and Freddie conforming 30 year fixed rate mortgages with full documentation of the loan. The first number is the cost for a 15 day lock, the second for a 30 day lock, and the third for a 45 day lock. A positive number means it costs that number of <a href=”http://www.searchlightcrusade.net/2019/12/what_are_points_and_how_do_the_1.html”target=”_blank”>discount points to get the rate. A negative number means that the lender will pay that many discount points for a loan done on those terms. I want to make the point that these are wholesale rates, but I didn’t feel like translating them to retail. I don’t work for free any more than you do, nor does any other loan provider.

5.625% 1.50 1.75 2.00
5.750% 1.00 1.25 1.50
5.875% .375 .625 .875
6.000% 0.00 0.25 0.50
6.125%-0.50-0.25 0.00
6.250%-1.00-0.75-0.50
6.375%-1.50-1.25-1.00
6.500%-1.75-1.50-1.25
6.625%-2.25-2.00-1.75
6.750%-2.50-2.25-2.00
6.875%-2.75-2.50-2.25
7.000%-3.50-3.25-3.00

As you should notice throughout, there is a 0.25 spread in costs between locking in any particular rate for 15 days as opposed to 30, or 30 days as opposed to 45. This is because it costs them money to have the money standing around doing nothing waiting for your loan to fund. The difference in costs between a 15 day lock and a 45 day lock at the same rate is half a point. When I wrote this, the column you wanted to pay attention to was the thirty day column. Due to regulatory changes and market changes, that’s not the case any longer. In point of fact, nobody actually locks the loan with a lender any longer until they have at least every ‘prior to documents’ condition satisfied with the underwriter, meaning the lender has agreed that there appear to be nothing in the borrower’s financial condition that would result in them rejecting the loan, and are prepared to draw up a final loan contract for signature. It costs the loan officer – and their company – too much if a loan is locked but not delivered.

When I started in this business, I locked every loan as soon as the customer said they wanted it. That meant a thirty day lock if you (the loan officer) were on the ball. You can’t do that any more without losing your shirt, because if you don’t fund at least seventy percent of what you lock, the lenders are going to refuse to do business with that loan officer, and they have surcharges on the loan officer if they fail to actually fund at least eighty percent of what they lock. Given how <a href=”http://www.searchlightcrusade.net/2020/01/getting_a_loan_in_a_paranoid_l_1.html”target=”_blank”>paranoid lenders have gotten, you’re going to have a certain number of applicants who flat out cannot qualify, and in at least one case out of ten, that failure is unpredictable just because nobody is the cookie cutter picture of an ideal underwriting scenario any longer.

Given regulatory changes, a loan officer has to be on the ball to get a refinance funded in two weeks from lock. Even if everything is ready to go, the lenders want a final redisclosure 7 days before signing documents, and with the <a href=”http://www.searchlightcrusade.net/2019/10/the_three_day_right_of_resciss.html”target=”_blank”>three day right of rescission on refinances it takes another week after signing to actually fund the loan. That’s once everything else is ready to go. You want the rate locked as early as practical, or you really have no idea whether it will be available when you get to the end of the process but other changes to the business make it prohibitively expensive to lock your loan at all before you have an underwriting commitment. Many providers work on a “promise the moon and wait and hope” basis, hoping the rates will drop. They get one loan for sure, when they lure you in with a low quote they cannot currently deliver, and if they get lucky and rates drop, you think they walk on water.

Now this is a fairly broad spread rate sheet, as the company was willing to take clients through a large range. On the other hand, at a 5/8ths of an additional point hit for 1/8th percent rate below 5.875, they were telling you that they really would prefer to keep their customer’s rates locked in for 30 years above that. On the other hand, since most people dispose of their old loans about every two years, most folks shouldn’t want to pay those costs, which will take much more than two years to recoup from the lower rate. It’s much the same phenomenon as insurance companies guarding against adverse selection (only those folks who have major health problems buying health insurance, for example).

Which loan is the best for you? Don’t know without more specifics. It depends on approximate loan amount, your life plans, your proclivities, and your financial situation.

But the devil is in the details, and one of the worst and most common devils is details is a provider “forgetting” the adjustments. Adjustments generally mean that the loan will be more costly than the basic rate/cost tradeoff outlined above, so “forgetting” to post the adjustments on a <a href=”http://www.searchlightcrusade.net/2020/11/the_2010_good_faith_estimate_p_2.html”target=”_blank”>Good Faith Estimate is one of the easiest and most effective ways to lie in order to make your loan look more attractive by comparison. Since most providers don’t guarantee their estimates, they can do this with basic impunity, but make no mistake – they know what the price is really going to be. If they won’t guarantee their estimates, ask them why not. Here are the possibly applicable adjustments for this category:

Loan amount under $60,000: half a point
Loan amount $60k up to $100k: quarter of a point
cash out loan, 70-80% <a href=”http://www.searchlightcrusade.net/2020/03/loan_qualification_standards_l_3.html”target=”_blank”>LTV: half a point
cash out loan, 80-90% LTV: three quarters of a point
Investment property 50-75% LTV: one and a half points
Investment property 75-80% LTV: two points
Investment property 80-90% LTV: two and a half points
No <a href=”http://www.searchlightcrusade.net/2020/07/impound_accounts_facts_and_faq_1.html”target=”_blank”>Impounds fee: quarter point
2 units 90-95% LTV: half a point
Manufactured home: three quarters of a point (they also have an absolute maximum CLTV of 80%)
Loan distribution
80/15/5 quarter of a point
75/20/5 quarter of a point
Interest only one and one eighths points
if CLTV over 90%: additional quarter point
97 percent of purchase price financed: three quarters of a point
100 percent of purchase price financed: one and a half points
2/1 <a href=”http://www.searchlightcrusade.net/2019/11/temporary_rate_buydowns.html”target=”_blank”>Buydown two and a half points
<a href=”http://www.searchlightcrusade.net/2019/11/levels_of_mortgage_documentati.html”target=”_blank”>Stated income FICO 680-699: half a point
Stated income FICO 700+: quarter of a point
(Stated Income loans are not available from any provider I’m aware of at this update)

So let’s see. If you are doing a cash out to 75 percent loan stated income and have a credit score of 690, you add one point to the costs listed above. (half a point for stated income at 690, half a point for cash out to 75%)

If you have an investment property duplex at 90 percent LTV, you would add three points (investment property loans are relatively expensive, as you can see, and it isn’t restricted to this lender. They are riskier loans)

Doing 100% financing on a $50,000 home: Two points. (when it was available)

One hopes you get the idea. To leave these out is a tempting omission for the less ethical providers. Just because they are left out does not mean you won’t pay them. You will. Usually they will spring them on you with the final closing documents and hope you don’t notice. Surprise!

(Between this profession and being a controller for twelve years, people should not wonder why I think that’s one of the ugliest words in the language).

Indeed, during my six weeks at the Company Which Shall Remain Nameless, I had no fewer than three screaming arguments with my supervisor over telling prospective clients the truth about adjustments. They didn’t want me to. I have this thing about telling clients the truth as best I know it.

Why do they do this? At signup, you have little emotional buy-in. At final loan docs, you are signing so much stuff that even a marginally skilled person who’s trying to distract you will be successful a lot of the time. The industry statistics say that over fifty percent literally never notice, at least until much later, after the transaction is irrevocable. And somewhere around eighty five percent of those who notice do just want the process to be over so badly that they will sign anyway, not to mention the fact that in the case of a purchase, they probably don’t have any choice at that point. They need the loan to get the house, without which they lose the deposit, and there is no more time remaining in the contract with which to go out and get another loan.

Caveat Emptor

Solicitation for Fraud and Conspiracy, or Entrapment?

An email I got Tuesday November 28, 2006:

My husband and I are not specifically on the market at the moment for a property but are always on the lookout for a great bargain. We have children, so school district is a big factor, but if the right place for the right price comes around, we’d definitely be interested in potentially buying a house, as we’re ready to settle down. We don’t mind a fixer-upper, but aren’t looking to do any major, “needs a contractor” work. Our price range is under 400K, as we intend to wrap any debt into our mortgage. We both have good jobs — I work for NAME DELETED as a loan specialist and he is a DELETED — but aren’t looking to kill ourselves with a mortgage payment, especially once you wrap taxes and insurance into the whole deal.

(emphasis mine)

Un-be-(censored)-lievable.

This person is a loan officer, and they’re wanting to do something that is FRAUD. I mean, I know it goes on, but to be propositioned cold, via the first email I got from this person, to commit a felony (or aid in its commission, thereby making me guilty of conspiracy, another felony) just blows my mind. Admittedly, this particular company is one where you don’t have to be licensed to work for them, but still, you should know the big issues like this, and perhaps at least pretend to have some respect for the law and good business practice.

My response?

You do realize that lenders don’t go along with this, don’t you? Purchase money loans if the purchase price is $400k and the seller gives you back 20k to pay off your debts, the effective purchase price is $380,000 – not $400,000. If you don’t conceal it the loan doesn’t work. If you do conceal it, it’s fraud.

I could use the business. But not so badly as to get involved in this.

No thank you.

Her response?

I may have misrepresented myself and my goals to you. Don’t be so quick to judge.

Oh, so now instead of soliciting my cooperation in felony fraud, she’s committing entrapment. And I’m supposed to think this is better.

Ladies and Gentlemen, I have a firm policy here of not naming specific malefactor companies or individuals (unless they pop up and name themselves!). Telling people how bad any one company in particular may be is beside the point of this website. I’m trying to give people the tools to use to judge as to whether or not they are being lied to, abused, etcetera in their specific instance – what people can do to prevent it, what they can do to improve their situation, what they should do if all the other tools fail and everything falls apart.

However, this one particular company represented by the alleged person in question is one on whom I have extensive amounts of evidence as to how bad their rates are, how misleading their business practices are, how badly they low ball their quotes, and in general, how shoddily they treat the customers that put money in their pocket. If I was going to list the two companies in the mortgage industry that (in my honest opinion) everyone should stay away from, this company would be on that list.

So it is very tempting to name names publicly, just this once. However, the lawyers would then get involved to no particularly good effect for anyone, and this very large company has a lot more resources than I do. Furthermore, I suspect, although I cannot prove, that I might be hurting a very few good loan officers who happen to work for this company in addition to all of the bad ones – and there are a lot of the bad ones working for this company. Finally, as I explained above, the point if this site is not revenge, and it’s not punishing evildoers. I am not the Count of Monte Cristo, nor am I a law officer, a prosecutor, or a judge. I’m a loan officer and a Realtor® who is also trying to give people real tools to judge their situations and achieve a better result. So if you are reading this, back off. I will not name names unless you force me to. But solicitations of fraud, and entrapment, from people who should know better and go out of their way to be jerks, really pisses me off, and if you want to force my hand, I really won’t regret it very much. I guarantee it will hurt you a lot worse than it will hurt me. Instead of trying to entrap me into a felony, just go away and pretend I don’t exist. The type of suckers who are your bread and butter don’t read this website anyway, or they sure as heck wouldn’t patronize your company!

Caveat Emptor

Selling to Avoid Foreclosure in a Buyer’s Market

Found this on a public forum

I need help to stop foreclosure on my home. I need to sell quickly? I am a couple months behind on my payments and want to sell now. I am not looking to make a profit just need to get what i owe.

Boy, did the sharks swarm over that one! There were at least a dozen offers to purchase before I saw it.

Anybody will buy your house for half the market value.

Contact an agent about selling at quick sale prices. Offer 2% listing agent, 3% buyers agent. Even a quick sale price should get you at least 80% of value. Yes, that will cost you 5%. But you’ll come out with 75% of value, net instead of 50. If your loan balance is anywhere under 75% of the value, this puts more money in your pocket. If your loan balance is more than that, it means you’ll owe less in taxes when the lender hits you with a 1099. Not to mention that trying to sell a short payoff without a good agent is an exercise in futility.

Now this is not to say that you should list it for 80% of your most fevered imagination of what it is worth. You need to sell, as in have someone offer a price that they can actually pay you. You need offers. Ideally, you want multiple offers fast. You do this by underpricing the market value of your property, so that you will attract people who want to look, and they think it’s a good price so they make an offer. The offer will not be full asking price, and don’t waste your time hoping that you will get such an offer. Once that Notice of Default hits, everybody knows that you need to sell. To use one example I’m going through with a buyer client right now, if your property is a two bedroom place that basically looks like wild animals have been living there, and your list price is 99% of the three bedroom down the street, you are not going to get it, and you have a deadline, while your prospective buyers do not. You need to figure out what it is really worth by sales of comparable property happening right now, and then you need to discount that price by enough to make a difference. How much? Depends upon what your local market is like. That’s part of what good agents get paid for.

Toss any concept of “negotiating room” or “getting what the property is worth out of your head. Get your attitude out of the seller’s market of two years ago. Especially in the current buyer’s market, all of the power is in the hands of the prospective buyers. If you won’t sell for what they offer, the one down the street who is a little bit smarter, or a little bit more desperate, will. Sellers have little enough power right now without the deadline of foreclosure. People who need to sell have only the power to say no, and what happens if they don’t say yes to someone? I’ll tell you what happens: You get nothing. The chances are better of flying to the moon by flapping your arms than of getting some of your equity back out of a foreclosed property. Since your best alternative is lose everything you have in the property, that’s not a strong negotiating position. This buyer does not have to have your property. With thirty seven sellers per buyer in my local market, they can go find a more attractive property, cheaper, from someone else. Their best alternative in negotiations is that they go find some other seller who will sell for what they want to offer. Negotiating position: Very strong. Net result, the buyer offers what the property is worth to them. If you won’t take it, they only need a bit of patience to find something else that will. If you didn’t need to sell, you could just hold on to the property, of course, but we’ve already determined that you don’t have that option, and time is not your friend. A very large proportion of agents still have their heads in seller’s market mode. Indeed, most of the major chains are still telling their agents to think like it’s a seller’s market. This kind of thinking is of no use in the present market, as roughly 46,000 residential property owners have discovered in San Diego County within the last year. Considering that only 31,000 transactions have successfully closed in the same time period (and the ratio is getting worse, not better), that is a sobering warning. Only about 40% of property owners who listed their properties sold at all, on any terms. When you consider the time constraints of selling under pending foreclosure, it behooves you to understand your position.

Caveat Emptor

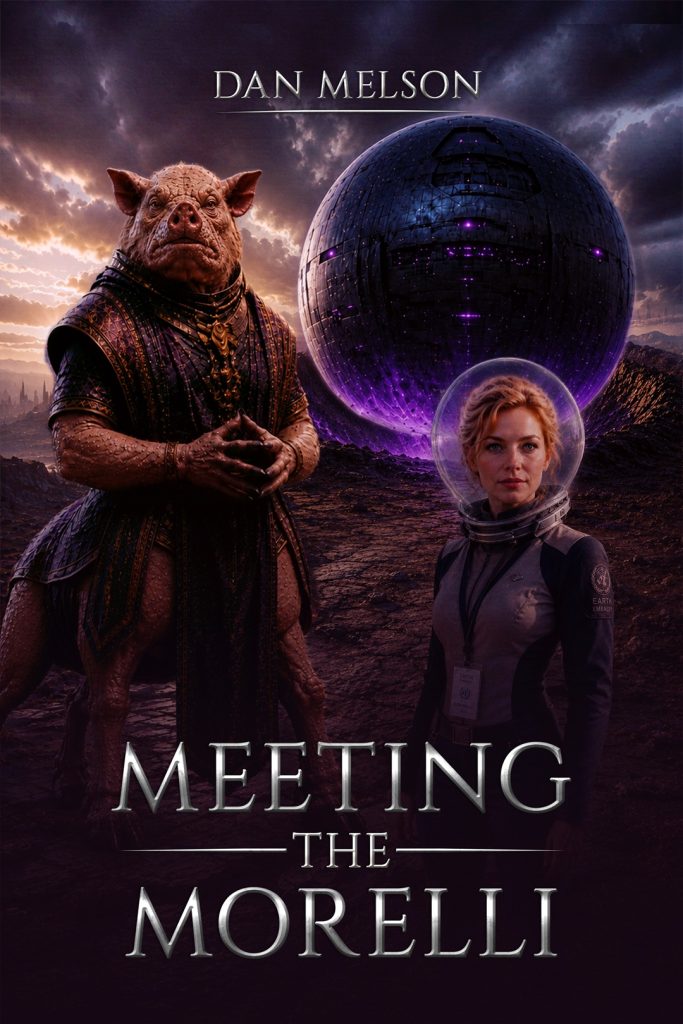
Release Day! Meeting The Morelli

Tessa was desperate, and a two year contract with an Imperial Embassy looked like the way out. Helping a newly contacted species develop to a point where they’re ready to deal with the universe is a years-long project, and those whose missions succeed can expect more lucrative contracts in the future as well as the knowledge they’ve helped an entire species survive.

The Empire of Humanity is not being altruistic. It has selfish reason to want the Morelli and others to survive. But the Morelli must be willing to learn, and there’s only so much latitude a species may be given before even the Empire’s own citizens require suppression or worse. Tessa and her superiors must find a way to persuade the Morelli to learn about the dangerous universe beyond their current holdings before the Morelli do anything irreversible.

Because evolution is not done when a species achieves sentience, or even technology. It becomes communal, and the penalty for failure is extinction.

Amazon Link: https://www.amazon.com/dp/B0HHWGLT2B

Books2Read Link: https://books2read.com/u/bzYwqn